World-class infrastructure and facilities to its clientele
Investment Case
Why this oppurtunity?
- Strategic Location - Located in the UAE with direct access to GCC, Indian Ocean, Red Sea and East African trade flows.
- Positioned Outside Congestion - Offers similar trade reach as Fujairah while avoiding congestion and operational bottlenecks.
- Strong Cost Position-Lower land lease costs and infrastructure support enhance baseline economics.
- Structural Demand - Regional storage capacity remains constrained, with continued increasing demand from energy andtrading markets.
- Scalable Platform - Phase 1 can be expanded with additional storage, services and terminal capabilities.
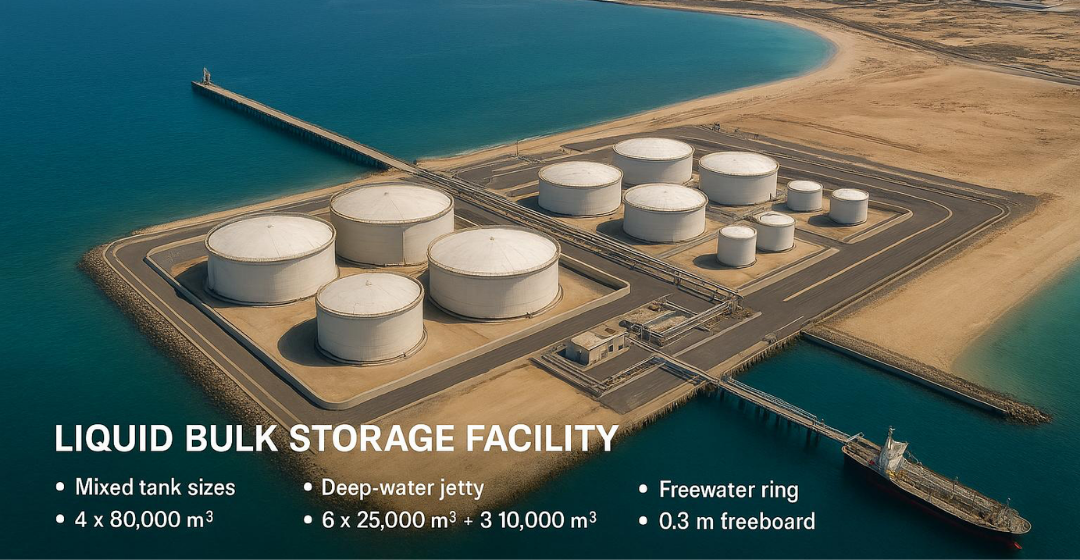
Terminal infrastructure lay-out example:
- 500,000 m³ storage capacity
- Multi-product tank configuration
- API-standard tank design
- Pumping and pipeline systems
- Marine and landside integration
- Terminal automation and control systems
- HSE and environmental systems
- Future expansion capability
Designed as a long-term commercial terminal platform.
Strategic Rationale
- Structural undersupply of liquid bulk storage in the GCC as crude production materially exceeds refining capacity
- GCC liquid bulk volumes growing ~5.5% CAGR, outperforming global trade growth
- Minimal sailing deviation (~1.5 hours) versus competing UAE ports, reducing fuel, charter costs and emissions• Cost-advantaged platform with ~30–50% lower land, labour and utilities vs regional peers
Asset & Technical Highlights
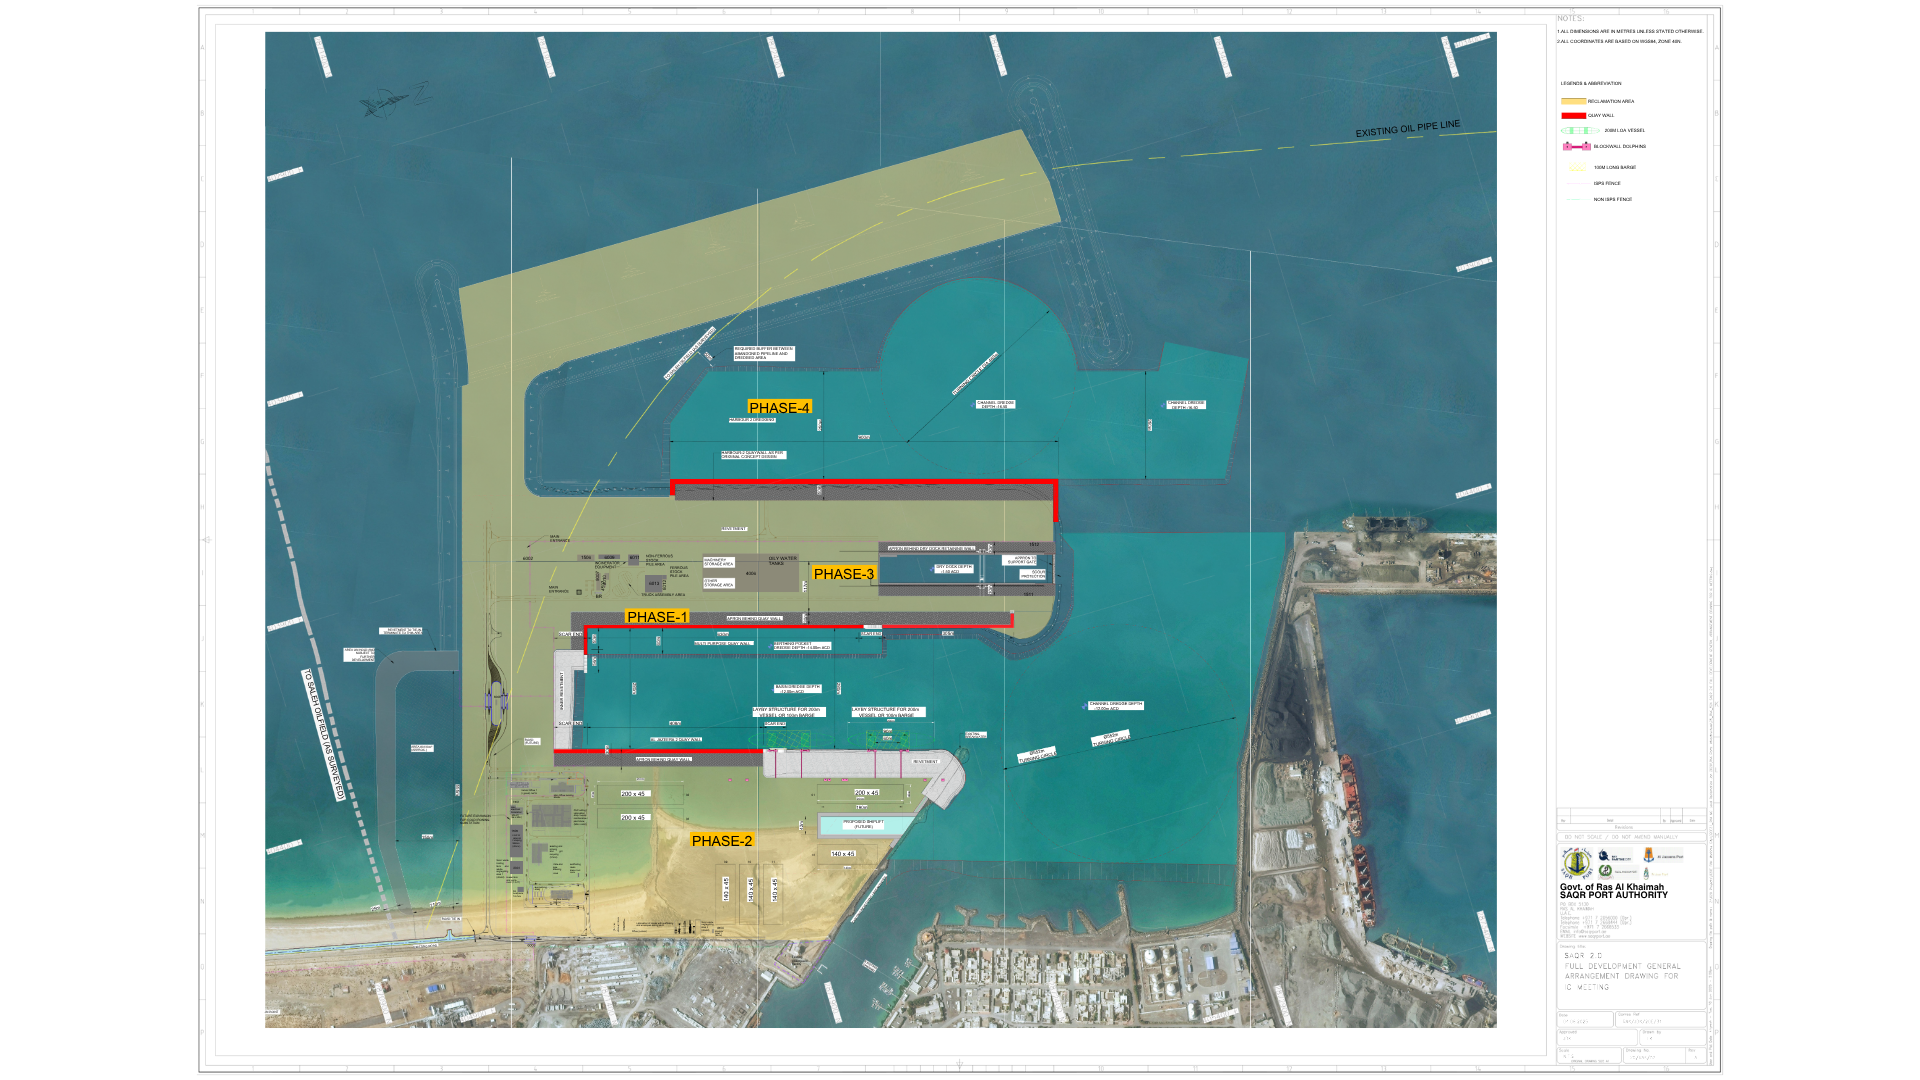
- Deep-water berths accommodating Aframax, LR2 and Suezmax tankers; SPM capability for VLCCs in Phase 2
- Drafts from ~14 m (Phase 1) expanding to 23 m+ in Phase 2
- Fully customizable tank farm and jetty configurations with no legacy infrastructure constraints
- Direct port-to-plot pipeline connectivity across >6 million sqm freezone land
- Zoned and permitted for future fuels including LNG, ammonia, methanol and biofuels
Commercial Model & Development Opportunities
Projects can be structured through:
- Long-term land lease
- Build-own-operate (BOO)
- Build-own-operate-transfer (BOOT)
- Joint venture
- Strategic anchor investor
- Industrial developer
- Terminal operator
Long-term land leases (25 years with possible extension) under UAE freezone regime
Headline Returns Logic (Indicative)
• Target unlevered IRR: 10–13%, consistent with core / core-plus infrastructure assets Levered equity IRR potential: 14–18% using conservative project-finance leverage
• Long-duration, resilient cashflows with downside protection from contracted volumes• Upside from Phase 2 expansion and energy-transition fuel adoption
Fee-Based, Infrastructure-Driven Revenues
Revenue is expected to be generated through:
- Storage lease agreements
- Throughput and handling fees
- Take-or-pay contracts
- Tiered tariffs based on volume and services
- Optional value-added services (blending, heating, etc.)
Commodity price exposure remains with customers. The terminal operates as a fee-based infrastructure asset.
Investment Thesis
Saqr 2.0 offers institutional investors exposure to a scalable, defensible port infrastructure asset in a structurallyundersupplied market. Backed by a government-owned sponsor, the terminal combines strong downside protection with expansion optionality, aligned with international ESG, safety and operational standards.
Driving Sustainable Impact Across the Globe

